Quick Answer
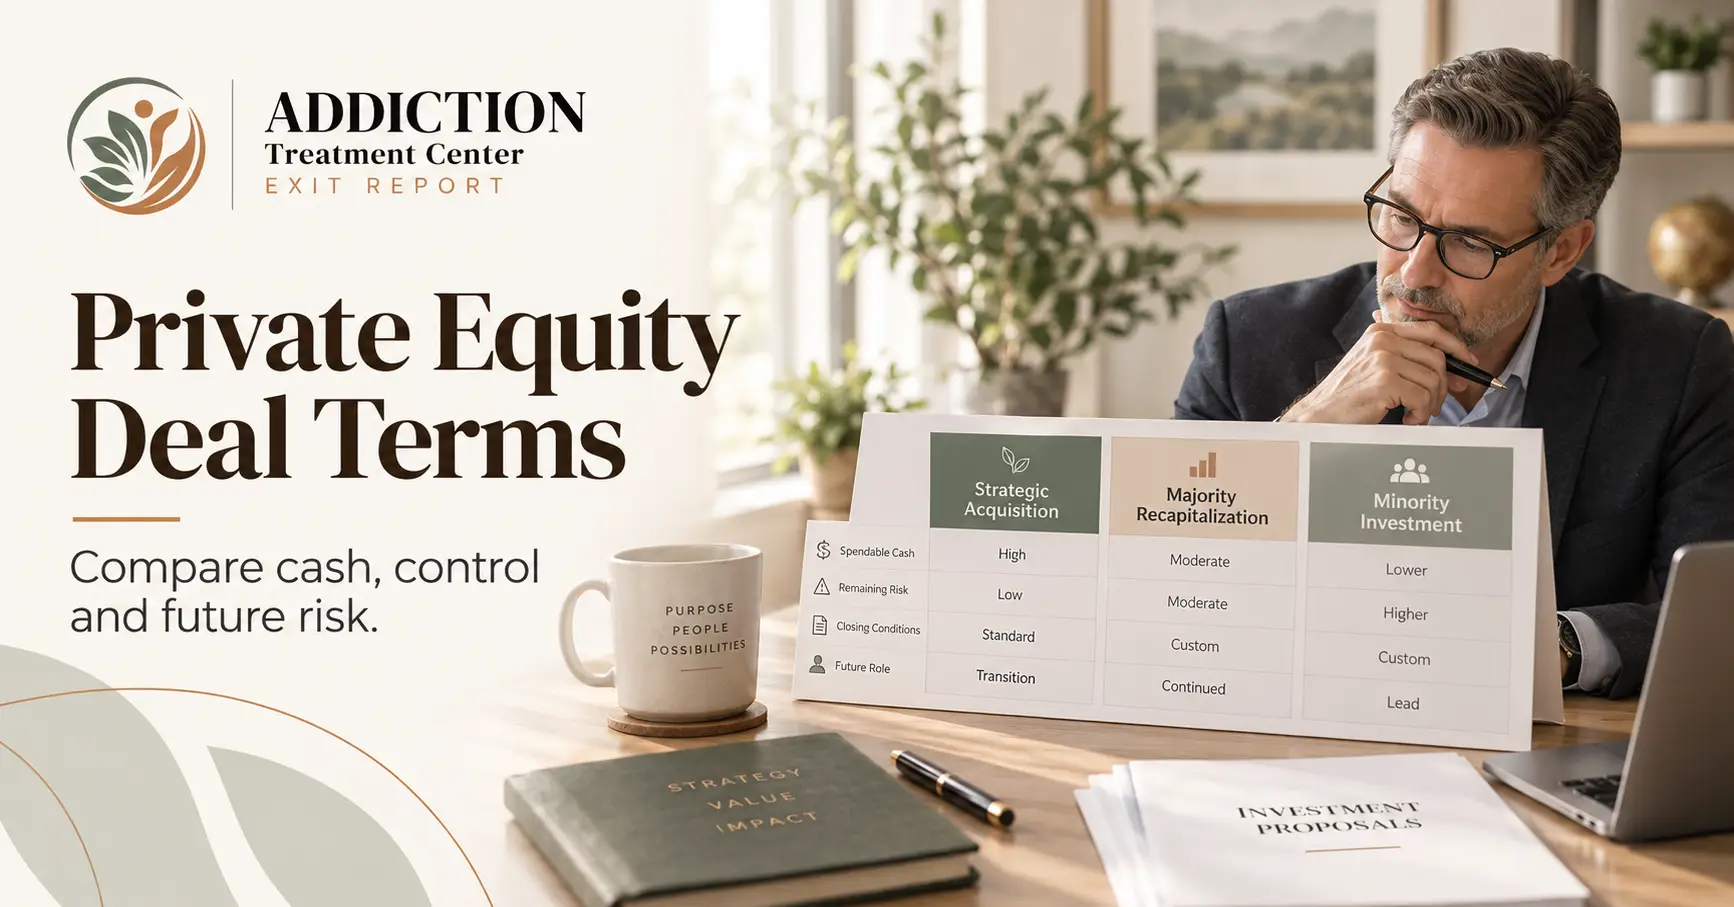
Owners evaluating addiction treatment private equity or another buyer should compare spendable cash, remaining investment risk, control, closing conditions and their future role. A strategic acquisition, majority recapitalization and minority investment can produce very different outcomes even when the stated valuation looks similar. Translate every offer into a common proceeds schedule, test contingent payments under realistic operating scenarios, and investigate the people who will control the business after closing.
Start your addiction treatment private equity review with the outcome you want
An owner can receive two credible offers and still be comparing different transactions. One buyer wants an established outpatient network with leadership in place. Another wants the owner to help build a larger platform. A third offers expansion capital while expecting the founder to continue operating the business. The valuation number alone cannot tell you which arrangement will work.
Before discussing terms, write down your minimum acceptable liquidity, how long you want to remain involved, which decisions you need to influence and how much of your wealth you are prepared to leave at risk. Include the practical obligations: a personally guaranteed lease, a clinical leadership role, family shareholders or a location you own separately. These considerations belong in the offer discussion, not in a hurried negotiation just before signing.
This guide focuses on choosing buyers and understanding deal terms for established U.S. addiction treatment and substance use disorder providers. It is a decision framework, not a valuation opinion or individualized legal, tax or investment advice. Residential, outpatient and opioid treatment businesses can require different structures and approvals. Comparing strategic and private-equity treatment-center buyers
Comparing strategic and private-equity treatment-center buyers
A strategic buyer is an operating organization pursuing a business reason for the acquisition. It may want additional locations, a complementary level of care, clinical capabilities or access to a market where it already has infrastructure. Ask which part of your organization it intends to preserve and which functions it expects to combine. Shared billing or purchasing may be attractive; a proposed change in clinical leadership deserves its own discussion.
Private equity describes an ownership and investment model. An investment firm may buy your company as a new platform, or an existing portfolio company may acquire it as an addition. The latter buyer is both a strategic operator and private-equity backed. Separating these labels avoids a misleading choice between two supposedly uniform categories.
For a platform transaction, investigate who will build the management team, fund additional investment and oversee integration. If the buyer expects you to recruit executives or acquire other programs, that is a substantial future job. For an add-on acquisition, focus on the existing operator’s systems, decision rights and ability to support your particular care model. Experience in residential treatment does not automatically demonstrate competence in running an OTP or an intensive outpatient network.
Other possibilities include independently financed operators, family-backed investment groups and organizations whose mission or tax status shapes their acquisition requirements. Judge each against evidence. Who has authority to approve the purchase? Which legal entity will owe the money? Does financing exist, or is the offer dependent on raising it? What happens if the buyer’s investment committee changes its view?
Ask to speak, with permission, to owners whose businesses the buyer acquired and to leaders still working there. Useful questions concern actual behavior: Were payroll and benefits ready on day one? How were staffing disputes handled? Did reporting demands match the original discussion? A buyer’s polished description of partnership becomes more meaningful when former sellers can explain how decisions were made under pressure.
Comparing SUD growth capital, recapitalization and a full sale
Growth capital usually aims to fund the business: hiring, systems, new sites or another acquisition. Seller liquidity aims to put money in an owner’s hands. A proposal can include both, but the distinction should be visible in its sources-and-uses schedule. An investment of several million dollars into the company does not mean the founder receives that amount personally.
A minority investment may let the founder retain a majority of the equity while sharing important decisions. Examine board composition, consent rights, restrictions on new borrowing, required budgets and the conditions for a future sale. An investor with a minority economic stake can still hold meaningful veto rights. The phrase “you remain in control” needs to be translated into the governing documents.
A majority recapitalization generally combines a change in control with continuing seller ownership. It can suit an owner who wants partial liquidity and a role in the next stage. It also exposes that owner to the new capital structure, other investors’ priorities and an uncertain exit date. Understand whether the retained interest sits in your original entity or in a parent company containing other businesses.
A full sale transfers the agreed ownership interest or business assets, but it may still leave the seller with transition duties, indemnity obligations, deferred consideration or an employment agreement. Clarify whether “full exit” means no equity, no operational responsibility, no financial exposure or all three. The documents may deliver only some of those outcomes. Comparing SUD growth capital, recapitalization and a full sale
To choose among these paths, test the downside before discussing upside. Would you still welcome the arrangement if expansion took longer, distributions stopped or your operating role became less enjoyable? A good match should remain workable when the investment plan misses its first forecast.
Translate the headline price into money you can use
Start with a written bridge from the stated price to expected seller proceeds. Establish whether the buyer is quoting enterprise value, equity value, a price for selected assets or a maximum package that includes contingent payments. Each term answers a different question. The offer should identify debt and debt-like deductions, treatment of cash, transaction expenses, working-capital adjustments and the portion delivered in something other than cash.
Separate four categories in your comparison: cash available at closing; cash withheld or deferred under contractual conditions; amounts payable only if future targets are met; and equity that remains invested. An escrow may eventually be released, but it is unavailable on closing day and subject to its agreement. A seller note is a credit exposure to a borrower. Neither should be described as immediately spendable proceeds.
Ask the accountant to model after-tax outcomes as well as pretax amounts. Asset and equity transactions can have different consequences, and consideration allocation matters. The IRS explains that a lump-sum business asset sale is treated as the sale of individual assets; qualifying asset acquisitions may require both parties to report the allocation on Form 8594. Structure and allocation should be discussed before the economics become difficult to change. IRS business-sale guidance and Form 8594 instructions.
Keep real estate visible. If you own the premises, determine whether the buyer is purchasing the property, taking a new lease or assuming an existing lease. Rent, repairs, guarantees and future relocation rights can shift value between the operating business and the property. A business price that looks attractive may rely on a below-market lease you would later regret.
Working capital can change the effective deal
A working-capital adjustment is intended to deliver an agreed level of operating assets and liabilities with the business. Its meaning comes from the purchase agreement. Do not assume that every buyer includes the same accounts or uses the same accounting policies. Request a sample closing statement using an actual recent month and trace every included balance.
Receivables deserve particular attention in a treatment business. A billed amount can differ substantially from expected cash. Agree on contractual adjustments, doubtful accounts, unresolved denials, patient balances, credit balances and recoupment reserves. Separate old receivables that the seller will retain from balances included in the purchase. Specify who collects retained accounts, who can settle them and how cash mistakenly received by the other party will be returned.
The target, sometimes called a peg, should reflect the operation being transferred and the agreed methodology. An average can be distorted by seasonal census, a payer payment interruption, a site opening or an unusual payroll date. Rather than arguing about a single number in isolation, show the monthly components and explain whether the period represents ordinary operations.
Watch for the same obligation appearing in two deductions. Accrued compensation, transaction bonuses, unpaid taxes or a payer exposure might be classified as working capital, debt-like items or a separate indemnity matter. The agreement should define the treatment and prevent duplicate recovery. Also specify how estimates will be finalized, the objection period, access to underlying records and how an independent accountant will resolve accounting disagreements.
Understand seller financing and claims after closing
A seller note means part of your payment remains dependent on the borrower. Identify the obligor, maturity, interest, payment schedule, security and any guarantee. Ask where the note ranks behind acquisition lenders and whether an intercreditor agreement can prevent payment or enforcement. Model the consequence of refinancing, a covenant breach or a sale of the borrower. A stated interest rate does not compensate for every restriction on collecting principal.
Indemnification provisions allocate responsibility for specified losses after closing. Review the subjects covered, monetary thresholds, caps, claim deadlines and exceptions with counsel. Known payer or regulatory issues may receive separate treatment. Compare the practical source of recovery and your remaining exposure, including whether claims can be deducted from an earnout or seller note. Avoid assuming that a negotiated escrow amount automatically caps every possible claim.
If representation-and-warranty insurance is proposed, ask the adviser and broker to explain the actual policy, exclusions, retention, premium allocation and any remaining seller obligations. The existence of insurance does not answer whether a particular billing issue or known investigation is covered. Read the policy and purchase agreement together.
These terms can change the appeal of otherwise similar offers. A buyer offering a little more cash but broad uncapped recourse may leave you with greater uncertainty than the offer sheet suggests. Have advisers summarize realistic exposure in ordinary language, including which obligations end on a specified date and which could remain longer.
Evaluating earnouts and rollover equity in a treatment-center sale
An earnout makes part of the price depend on future performance or another specified event. It can bridge a genuine disagreement about what a new site or recently changed payer contract will produce. It can also shift risk to an owner who no longer controls the decisions affecting the result. The useful question is whether the measure, operating rights and dispute process make the payment understandable and reasonably influenceable.
For a revenue-based earnout, define whether the measure is charges, net revenue or collected cash; which services and locations count; and how refunds, recoupments and late collections are handled. For an earnings-based earnout, address corporate allocations, management fees, integration expenses, staffing changes and accounting consistency. A simple percentage is not a complete formula.
Discuss buyer-controlled actions explicitly. What if the buyer closes a program, moves referrals, changes rates, replaces billing software or postpones hiring? Negotiate information rights, calculation statements, review access and the remedy for actions that undermine the agreed measurement. Work through an ordinary month, a bad month and a delayed-payment month using the proposed language.
Health care counsel should examine payment incentives and ongoing compensation. Federal anti-kickback rules can apply to remuneration tied to federal health care program business, while the Eliminating Kickbacks in Recovery Act addresses prohibited referral remuneration involving specified recovery homes, clinical treatment facilities and laboratories. Applicability and exceptions depend on the facts. An earnout or employment bonus should never be treated as a ready-made exception merely because it appears in a purchase agreement. OIG fraud-and-abuse guidance and 18 U.S.C. § 220.
Rollover equity is a continuing investment. Identify the issuing entity, security class, entry valuation, liquidation preferences, distribution rules and debt ahead of your interest. Ask how future acquisitions, management incentives and new capital could dilute you. Review transfer restrictions, information rights, tag-along and drag-along provisions, and what happens if you leave employment. A percentage without those terms provides an incomplete picture of ownership.
Private securities can be illiquid, and the SEC warns investors to understand transfer restrictions and the possibility of holding an investment indefinitely. Your rollover documents require their own review; the buyer’s projected exit is a scenario rather than a promised cash date. Do not assume tax deferral either: have tax counsel analyze the actual structure. SEC private-placement investor bulletin.
Your retained role needs its own negotiation
If you will stay, negotiate the role while you still have meaningful leverage. Define responsibilities, reporting lines, budget authority, expected hours, work location, compensation and the intended duration. A title such as president or clinical adviser says little about whether you can approve hiring, influence services or decline a growth initiative.
Read employment, consulting and equity documents together. A termination provision may affect both salary and the price at which the company can repurchase your rollover interest. Examine cause, good reason, disability, death, severance and dispute provisions. Restrictive covenants also deserve state-specific legal review. Do not rely on a general assurance that you can “do something else” later.
For an owner who is also a treating professional, distinguish clinical obligations from business-management duties. Identify who makes patient-care decisions and how disagreements about staffing, utilization review or service changes are escalated. A buyer should be able to describe its clinical governance in operational terms. If protecting a service is central to your decision, discuss what can be made enforceable and for how long instead of relying solely on a statement of shared values.
A hypothetical comparison of two offers
The following invented example illustrates structure only. It is not a market valuation, transaction precedent or recommendation. Assume both offers buy the same business, use the same working-capital target, include no excess cash and face identical seller debt of $1 million and transaction expenses of $250,000. Taxes are excluded.
Offer A states a $10 million enterprise value. It requires no rollover or earnout and withholds $500,000 in escrow. Estimated cash at closing is therefore $8.25 million: $10 million less debt, expenses and escrow. If the full escrow is later released and no other adjustments apply, total pretax cash received would be $8.75 million.
Offer B is described as “up to $12 million.” Its fixed enterprise value is $10 million, plus a maximum $2 million earnout. It also requires $2 million of rollover equity and the same $500,000 escrow. On these stated assumptions, cash at closing is $6.25 million: the fixed $10 million less debt, expenses, escrow and rollover. The seller additionally holds equity initially valued at $2 million and may receive earnout and escrow payments.
The $12 million headline does not create a $3.75 million improvement over Offer A’s closing cash. It combines different kinds of value. Offer B delivers $2 million less cash immediately, maintains investment exposure and adds a performance contingency. The rollover could rise in value, remain illiquid or lose value; the earnout could pay nothing, part or all of its maximum.
An owner prioritizing retirement liquidity might favor A even before negotiating employment terms. An owner who wants to keep building and understands B’s governance may prefer B. Both should run the same downside cases: a payer interruption, slower collections, an early employment departure and a delayed future exit. Reconcile the comparison again whenever the legal drafts change the economics.
Choose the terms you can defend before exclusivity
Prepare one offer sheet per bidder with identical headings: fixed value, immediate cash, contingent value, equity retained, working-capital treatment, financing, approvals, seller obligations and retained role. Add unresolved items rather than giving the buyer credit for terms it has not offered. If one proposal omits indemnity caps or rollover repurchase rights, the blank is a negotiation item.
Ask counsel which parts of the letter of intent are binding. Exclusivity, confidentiality and expense provisions can create obligations even when the purchase itself remains conditional. Set an exclusivity period that fits the remaining work, require concrete diligence progress and identify what happens if financing or approvals stall. A generous headline should not buy unlimited time to renegotiate.
Finally, distinguish willingness to sign from ability to close and operate. Request a credible approval plan for the actual entity and services being transferred, including state, payer and program requirements where applicable. Evaluate a buyer’s ability to keep the organization stable alongside its economic offer. A well-matched agreement gives you a clear understanding of the money, the remaining risk and the work expected after closing.
Discuss the choices in the context of your business
If you are weighing buyers, outside capital or competing structures, Olympic M&A’s behavioral health advisory team is a starting point for discussing your objectives and transaction options. Bring a plain-language list of the outcome you want, your constraints and the terms already proposed. Your legal and tax advisers should evaluate the actual documents before you commit.
Frequently asked questions
Is a strategic buyer better than private equity for a treatment center?
There is no universal winner. A strategic operator may offer useful infrastructure or a simpler integration path, while a private-equity-backed buyer may support expansion and continuing ownership. The categories overlap. Compare the actual decision-makers, financing, clinical governance, contractual protections and transition requirements rather than choosing from the label alone.
What does a minority recapitalization mean for an owner?
It generally involves selling or issuing a minority ownership interest, potentially with proceeds split between shareholder liquidity and company funding. Majority ownership does not necessarily preserve unrestricted control. Board seats, veto rights, borrowing restrictions, distribution provisions and future-sale rights determine how the relationship works.
Should I count an earnout as part of my retirement proceeds?
Model it separately from closing cash. Its value depends on the contract, performance and the buyer’s ability to pay. Test a zero-payment case before relying on it for fixed obligations. An accountant and transaction counsel can help assess the formula, tax timing, operating protections and dispute process.
Does rollover equity guarantee a second payout?
No. It leaves you invested in a private business, with exposure to operating performance, leverage, dilution, security terms and exit timing. Ask what entity you own, where your interest ranks and what liquidity rights exist. A forecasted future sale price should not be treated as a guaranteed return.
Can a full sale still require me to keep working?
Yes. A buyer may require a transition, employment or consulting agreement even if you sell all your equity. Negotiate the duration and responsibilities separately, then review their connections to deferred payments, restrictive covenants and termination rights. “Full sale” should be defined by the documents, not the marketing description.
What should I resolve before signing a letter of intent?
Aim to resolve the price definition, cash and equity mix, earnout concept, working-capital approach, financing conditions, retained role and major approval dependencies. Have counsel review binding provisions and exclusivity. Leaving every difficult issue for definitive documents can make later comparisons and negotiations much harder.